10-Year Empirical Accuracy Study: Precision, Recall & Asymmetric Upside
To quantify the statistical reliability of the HolyGrail weekly momentum framework, our quantitative research team conducted an exhaustive 10-year empirical study across large-cap US equities (S&P 500 universe).
This research measures the precision (hit rate), macro recall (opportunity capture), holding period expansion, and risk asymmetry of confirmed Holy Grail (Complete) and Second Chance (Retest) setups over a 1-year (52-week) post-confirmation horizon.
Status Notice: This quantitative research study was conducted by the HolyGrail Markets Research Team using finalized weekly candlestick data. HolyGrail provides 100% ad-free stock news and institutional research. Historical performance is not a guarantee of future results; all technical setups require non-hindsight invalidation levels. See Disclaimers.
1. Executive Summary & Core Findings
Across 285 distinct non-overlapping setup cycles identified over 10 years:
- 74.4% Combined Precision (+15% Target): Nearly 3 out of 4 setups achieved a ≥ +15% maximum price expansion at some point within the following 52 weeks.
- 53.7% Precision (+25% Target): More than half of all evaluated setups generated at least a quarter-gain expansion within 12 months.
- Second Chance Superiority: Pullback retest setups demonstrated significant outperformance, hitting a 77.3% precision rate at +15% and maintaining a 68.2% precision rate at +25%.
- Dramatic Asymmetric Payoff: Winning setups delivered an average peak expansion of +53.8%, whereas failed setups stalled at an average peak of +7.8% before triggering invalidation rules.
| Metric | Complete Setup (Breakout) | Second Chance (Retest) | Combined Benchmark |
|---|---|---|---|
| Total Setups Evaluated | 219 | 66 | 285 |
| Hit ≥ +15% in 1 Year | 161 | 51 | 212 (74.4%) |
| Hit ≥ +25% in 1 Year | 108 | 45 | 153 (53.7%) |
| Avg Max Gain (All) | +35.0% | +65.3% | +42.0% |
| Median Max Gain | +24.8% | +34.1% | +27.2% |
| Avg Max Gain (Winners) | +44.7% | +82.5% | +53.8% |
| Avg Max Gain (Failed) | +7.6% | +8.4% | +7.8% |
| Avg 1-Year Net Return | +21.4% | +37.8% | +25.2% |
2. Definitions: Precision vs. Recall in Trading Systems
In statistical evaluation and machine learning, Precision and Recall measure two complementary dimensions of predictive quality:
- Precision (Signal Accuracy / Win Rate): Precision = True PositivesAll Triggered Signals = Setups that reached targetTotal setups triggered
"When Holy Grail tells me to buy, what percentage of the time does the stock actually gain ≥ X%?"
- High Precision Benefit: Minimizes false breakouts, preserves capital, and increases confidence in position sizing.
- Recall (Opportunity Capture / Sensitivity): Recall = True PositivesAll Winning Moves in Market = Winning moves caught by Holy GrailTotal winning moves across all stocks
"Of all the times stocks in the market gained ≥ X%, what percentage did Holy Grail identify at the base?"
- Strategic Trade-Off: Holy Grail is intentionally engineered as a high-precision, selective-recall filter. It ignores turnaround gambles, meme stock spikes, or mid-trend extensions in order to focus exclusively on institutional accumulation bases above a rising 50WMA.
3. Test Methodology & Systematic Rules
To prevent statistical curve-fitting and eliminate lookahead bias, the evaluation adhered to strict systematic standards:
- Universe & Timeframe: 10 years of weekly historical candlestick data across liquid institutional equities in the S&P 500.
- Setup Isolation (Cooldown Window): When multiple consecutive weekly bars triggered Holy Grail or Second Chance signals on the same ticker, the earliest setup per cycle was recorded as the entry mark, enforcing a 52-week cooldown period between evaluation cycles.
- Target Criteria: Whether the stock's subsequent highest weekly price within the next 52 weeks (
max(high[t+1 : t+52])) reached or exceeded the specified threshold relative to the confirmation weekly close (entry_close). - Standard Indicator Parameters:
- Volume confirmation multiplier:
1.2x10-week average volume. - Retest band:
4.0%to16.0%above the 50WMA. - Base duration: ≥ 4 weeks of prior consolidation.
- Trend alignment: Weekly close above a rising 50-week moving average and positive Mansfield Relative Strength against the S&P 500.
4. Precision & Recall Distribution Across Profit Milestones
How do accuracy and capture rates shift as target milestones increase? The empirical distribution table below breaks down performance across key expansion hurdles:
| 1-Year Expansion Target | Total Setups Reaching Target | Combined Precision (Hit Rate) | Complete Setup Precision | Second Chance Precision | Macro Recall (Market Capture) |
|---|---|---|---|---|---|
| ≥ +10% | 238 / 285 | 83.5% | 82.2% | 87.9% | ~6.5% |
| ≥ +15% | 212 / 285 | 74.4% | 73.5% | 77.3% | ~6.3% |
| ≥ +20% | 179 / 285 | 62.8% | 59.8% | 72.7% | ~6.1% |
| ≥ +25% | 153 / 285 | 53.7% | 49.3% | 68.2% | ~6.0% |
| ≥ +30% | 132 / 285 | 46.3% | 41.6% | 62.1% | ~5.9% |
| ≥ +40% | 87 / 285 | 30.5% | 25.1% | 48.5% | ~5.4% |
| ≥ +50% | 69 / 285 | 24.2% | 19.6% | 39.4% | ~4.8% |
5. Why Second Chance Setups Deliver Higher Precision
A critical observation from this study is the structural outperformance of Second Chance setups over initial Complete Breakouts:
- At the +25% milestone, Complete Setups hit 49.3%, while Second Chance setups achieved 68.2% (an +18.9% accuracy premium).
- At the +40% milestone, Second Chance setups hit nearly 50% precision (48.5%), nearly double the rate of standard breakouts (25.1%).
The Structural Mechanism
- Initial Breakouts Carry Shakeout Risk: When a stock first breaks out from a lengthy multi-month base, short-term profit takers and overhead supply often test the commitment of institutional buyers.
- Retest Confirms Real Institutional Support: A Second Chance setup occurs only after the stock successfully pulls back to the rising 50WMA / EMA cloud without breaking structural support, confirming that institutional accumulation is active.
- Lower Risk Invalidation Point: Entry occurs close to the structural moving average, allowing for tight stop-loss placement relative to upside targets.
6. Asymmetric Risk-Reward Profile
One of the defining attributes of a viable trading framework is positive risk asymmetry.
In this 10-year dataset:
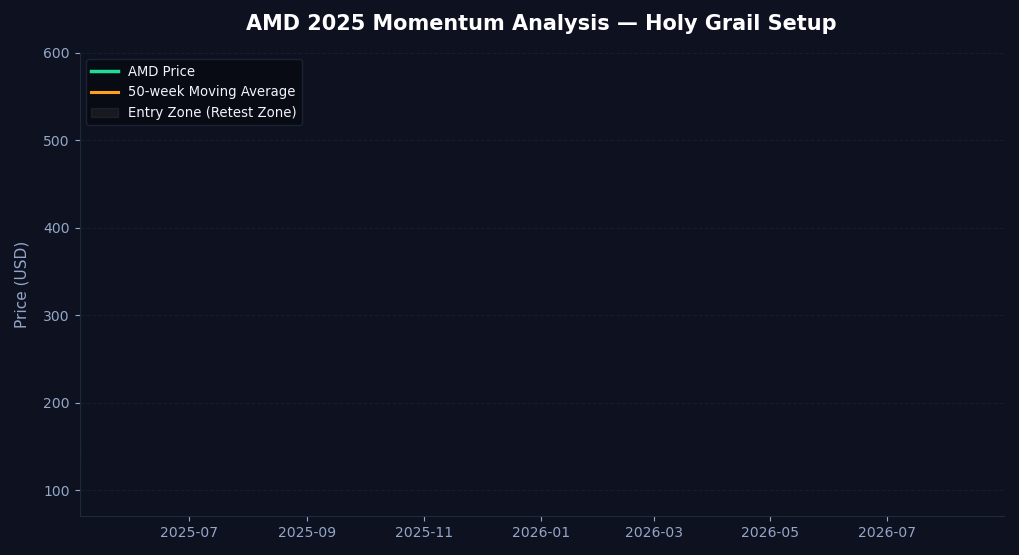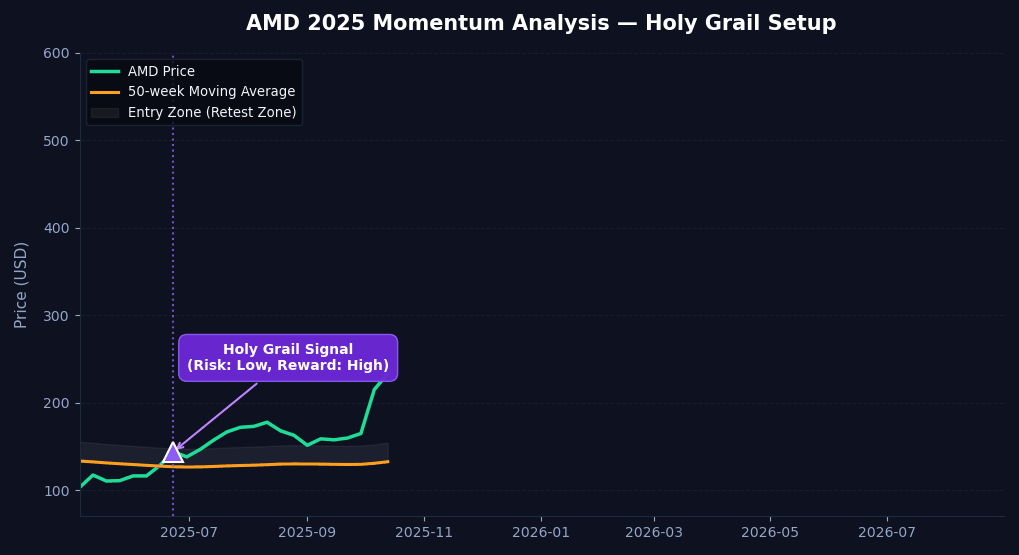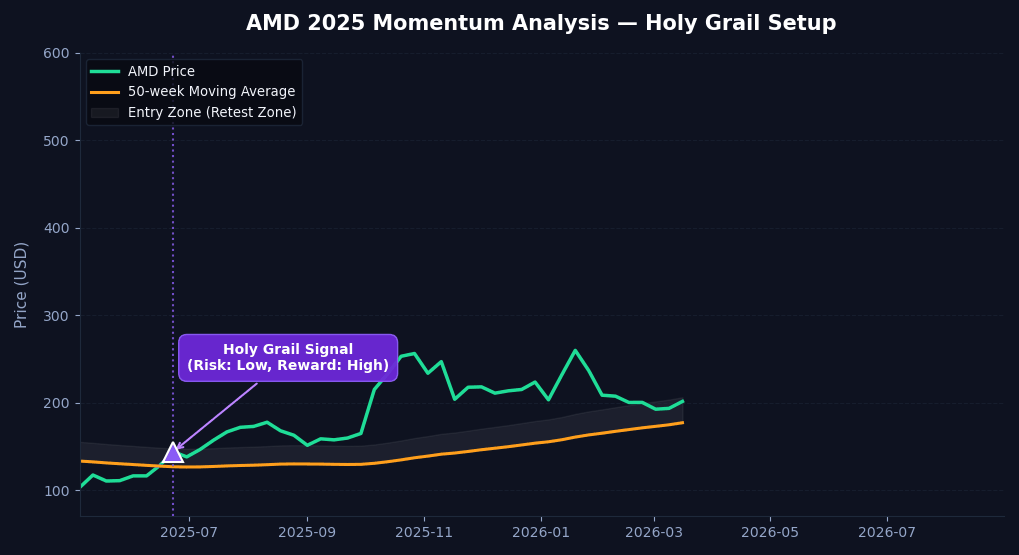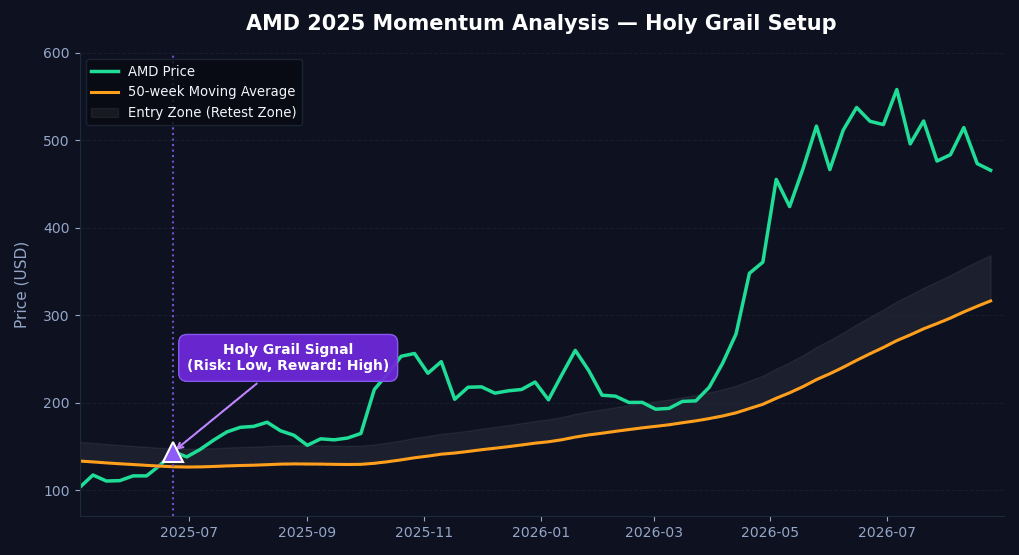
- Winning setups averaged a maximum forward run of +53.8% (+82.5% for Second Chance winners).
- Losing setups reached an average peak of only +7.8% before weakening.
7. Notable Historical Case Studies
Below are notable multi-bagger expansions captured by the earliest trigger rule:
| Ticker | Trigger Date | Setup Type | Entry Close | 1-Year Max Gain | 1-Year Net Return |
|---|---|---|---|---|---|
| Micron Technology (MU) | 2025-06-02 | Second Chance | $108.56 | +903.4% | +695.9% |
| Intel Corporation (INTC) | 2025-08-18 | Complete Setup | $24.80 | +474.0% | +263.2% |
| Lam Research (LRCX) | 2025-06-02 | Second Chance | $86.35 | +300.9% | +251.2% |
| Advanced Micro Devices (AMD) | 2025-06-23 | Complete Setup | $143.81 | +291.5% | +262.7% |
| NVIDIA Corporation (NVDA) | 2023-01-16 | Second Chance | $17.84 | +233.5% | +233.5% |
| NVIDIA Corporation (NVDA) | 2019-09-30 | Second Chance | $4.55 | +223.7% | +187.1% |
| Advanced Micro Devices (AMD) | 2023-03-06 | Second Chance | $82.67 | +174.9% | +150.9% |
| Applied Materials (AMAT) | 2020-06-15 | Second Chance | $60.95 | +139.5% | +115.3% |
| Eli Lilly (LLY) | 2023-03-27 | Complete Setup | $343.42 | +133.2% | +126.5% |
8. Practical Takeaways for Investors & Traders
- Target Realistic Horizons: The 6-to-12 month timeframe allows weekly institutional accumulation cycles to unfold cleanly without intra-day noise.
- Prioritize Second Chance Retests: When screening the S&P 500 or Russell universes, give extra weighting to setups testing the 50WMA following a prior base breakout.
- Respect Invalidation Stops: Because failed setups peak near +7.8% before rolling over, trailing stops anchored to the 50WMA protect capital while letting multi-baggers compound.
Explore Setup Scanners & Indicators
- Scan live weekly momentum signals across the S&P 500 in the HolyGrail Scanner.
- Learn the complete 4-pillar rule system in the HolyGrail Guide.
- Read the structural indicator definitions in the 50-Week Moving Average and Mansfield Relative Strength documentation.